Capex Arms Race: Mapping Hyperscaler AI Spend and What It Buys
Mapping Big Tech AI capex: what hyperscalers spend on chips, data centers and power—and how debt, delays and depreciation reshape the arms race.
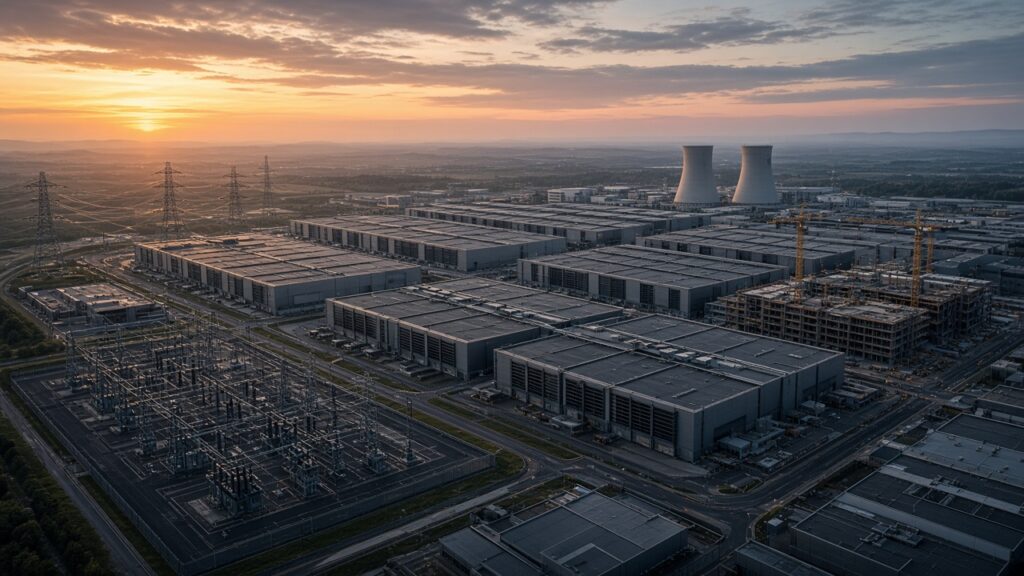
Every quarter, the earnings season now doubles as an infrastructure census. Between 21 and 29 October 2026, Meta, Microsoft, Alphabet and Amazon reported their September-quarter results, and the combined message was simple: AI capex is still climbing, the bills are getting larger than the cash flows that used to pay for them, and the bottleneck has moved from money to physical delivery — chips, buildings and power.
This piece maps what the largest buyers of compute actually reported, how their numbers differ by definition, and — the more interesting question — what all that hyperscaler AI investment is buying.
The latest prints, company by company
All figures below come from the companies’ own earnings releases, SEC filings or earnings calls. Note the periods: Microsoft and Oracle run fiscal years that do not match the calendar.
| Company | Period | Reported capex | Definition | Full-year outlook |
|---|---|---|---|---|
| Amazon | Q3 2026 (Jul–Sep) | $77.3B | Purchases of property & equipment (gross) | ~$220B cash capex for 2026 |
| Alphabet | Q3 2026 (Jul–Sep) | $51.4B | Purchases of property & equipment | $195–205B for 2026 (unchanged) |
| Microsoft | Q1 FY2027 (Jul–Sep 2026) | $45.2B | Incl. $7.4B finance leases; cash PP&E $39.4B | ~$170B for calendar 2026 |
| Meta | Q3 2026 (Jul–Sep) | $34.91B | Incl. principal payments on finance leases | $135–145B for 2026 |
| Oracle | Q1 FY2027 (Jun–Aug 2026) | $28.5B | Capital expenditures (cash flow statement) | $90–95B for FY2027 |
Amazon: the biggest single cheque
Amazon’s cash flow statement for the three months to 30 September 2026 shows $77.259 billion in purchases of property and equipment, more than double the $35.095 billion of the same quarter in 2025. Netting out $1.381 billion of proceeds from asset sales and incentives gives roughly $75.9 billion, the “cash capex” measure CFO Brian Olsavsky said “primarily relates to AWS and AI.”
On a trailing-twelve-month basis, net purchases of property and equipment reached $210.7 billion. That pushed trailing free cash flow to an outflow of $42.4 billion, against an inflow of $14.8 billion a year earlier; the company’s release attributes the $94.8 billion year-over-year increase in net capex primarily to investments in artificial intelligence. The 10-Q also shows $48.1 billion of long-term debt proceeds in the quarter alone. In its Q3 release, Amazon said it continues “to expect 2026 cash capital expenditures to be approximately $220 billion.” Meanwhile AWS operating income rose to $17.8 billion from $11.4 billion — evidence that the spend is landing on a growing, profitable business, even if the cash returns lag.
Alphabet: servers first, buildings second
Alphabet’s 8-K exhibit reports $51.355 billion of purchases of property and equipment in Q3 2026, versus $23.953 billion a year earlier, and $131.95 billion for the first nine months of the year. CFO Anat Ashkenazi gave one of the most useful splits of the season: roughly 65% of Q3 technical-infrastructure investment went to servers and networking equipment (useful lives of about six years), and 35% to data centers (seven to 40 years).
Alphabet kept its 2026 guidance at $195–205 billion and said it expects capex to “increase significantly in 2027.” Quarterly free cash flow was negative $9.1 billion, also affected by inventory built up for TPU system sales and a $5.2 billion EC fine payment. The payoff side is visible too: Google Cloud revenue rose 103% to $30.7 billion, with TPU system sales cited as a meaningful contributor.
Microsoft: delayed capacity, not lower ambition
Microsoft’s fiscal Q1 2027 (July–September 2026) capex was $45.2 billion, including $7.4 billion of finance leases; cash paid for PP&E was $39.4 billion. CFO Amy Hood said the total came in lower than planned because “some third party capacity deliveries we expected in Q1 were delayed.” Roughly three quarters went to short-lived assets — primarily CPUs and GPUs, including higher memory and storage costs.
For the December quarter, Hood guided to more than $50 billion, and to approximately $170 billion for calendar 2026, citing those third-party delays — down from a prior figure of about $175 billion given in July, as reported by CNBC. Microsoft has historically remained free-cash-flow positive (FCF was $18.6 billion in the quarter) and expects to stay so in FY2027, while signalling it will tap additional funding sources when attractive.
Meta: the narrowest range
Meta reported Q3 2026 capital expenditures, including principal payments on finance leases, of $34.91 billion, and narrowed its 2026 outlook to $135–145 billion from $130–145 billion. Free cash flow for the quarter was negative $2.12 billion. On 2027, the company said only that it is still developing its budget and capacity plans.
Oracle: the leveraged challenger
Oracle is smaller but spending at a startling rate relative to its size. Capex in fiscal Q1 2027 (June–August 2026) was $28.499 billion, versus $8.502 billion a year earlier — and more than half of Oracle’s entire fiscal 2026 total of $55.663 billion. An unusual feature: $11.363 billion of the quarter’s operating cash came from customer prepayments with a significant financing component, so management put net cash capex at about $18 billion. On the call, Oracle reiterated $90–95 billion of capex for FY2027, with no more than $70 billion in net cash capex, and noted it had completed a $20 billion equity issuance.
Adding it up — carefully
Summing the latest quarters gives roughly $237 billion for the five companies (Amazon $77.3B, Alphabet $51.4B, Microsoft $45.2B, Meta $34.9B, Oracle $28.5B). Taking the midpoints of the four calendar-2026 guides from Amazon, Alphabet, Microsoft and Meta yields roughly $730 billion of Big Tech AI spend for the year.
Treat these totals as an order of magnitude, not an accounting figure. The definitions differ: Microsoft and Meta count finance leases at commencement, which pulls future lease obligations into today’s capex; Alphabet reports cash purchases; Amazon’s “cash capex” is net of incentives; Oracle’s quarter ends in August. Not every dollar is AI, either — warehouses, offices and general cloud still absorb some of it — but every management team now names AI infrastructure as the main driver.
What the money actually buys
1. Accelerators and servers: the short-lived majority
The single clearest trend of 2026 is the mix shift toward short-lived assets. Microsoft says about 75% of quarterly capex now goes to CPUs and GPUs; Alphabet puts servers and networking at about 65% of technical-infrastructure spend. These are assets depreciated over roughly six years or less, which means the capex wave becomes a depreciation wave: Alphabet’s quarterly depreciation of property and equipment rose to $8.4 billion from $5.6 billion a year earlier, and Oracle’s to $3.2 billion from $1.4 billion.
This is where the foundation-model race shows up in the ledger. Training frontier models and, increasingly, serving agents and inference at scale consume accelerator fleets — Nvidia GPUs, Google’s TPUs, Amazon’s Trainium and other in-house silicon. Microsoft explicitly flagged rising memory and storage prices, a reminder that high-bandwidth memory has become a cost line of its own.
2. Data center shells, land and cooling: the long-lived base
The other third or so buys concrete, steel, electrical rooms and cooling plants — assets with lives of seven to 40 years by Alphabet’s accounting. Density is what makes these buildings different from the cloud halls of a decade ago: racks of liquid-cooled accelerators draw far more power per square metre, forcing new designs for cooling, floor loading and power distribution. These outlays are slower to turn into revenue, but they set the ceiling on how many chips can be installed later.
3. Leased and third-party capacity
Not all capacity is owned. Finance leases put $7.4 billion into Microsoft’s quarterly number, and Microsoft attributed its shortfall to delays at third-party capacity providers — the so-called neoclouds and GPU-as-a-service suppliers. This hybrid model lets hyperscalers add compute faster than they can build, but it also makes their capex timing dependent on other companies’ construction schedules.
4. Networking
Tens of thousands of accelerators only behave like one computer if they are wired together. Alphabet’s 65% bucket explicitly bundles servers and networking: switches, optics and the interconnects inside and between data centers. As training clusters scale, the network becomes a material share of every rack.
5. Power — the line nobody reports
Here is the gap in the disclosures: none of the five reports capex in megawatts, and energy procurement mostly sits outside capex in long-term power purchase agreements. Yet power availability is now the binding constraint on how fast capex can be deployed. Oracle was a partial exception: its fiscal Q1 2027 release cited the delivery of 850 MW of additional data center capacity in the quarter. For readers, the practical lesson is that the dollar guides only become compute when grid connections, substations and generation arrive on schedule — and Q3 showed that schedules can slip.
Who pays: the financing turn
For years, Big Tech funded capex from operating cash flow with room to spare. That is no longer universally true:
- Amazon: trailing free cash flow of −$42.4 billion and $48.1 billion of new long-term debt in one quarter.
- Alphabet: quarterly free cash flow of −$9.1 billion.
- Meta: quarterly free cash flow of −$2.12 billion.
- Oracle: quarterly free cash flow of about −$5.4 billion, partly offset by customer prepayments and a $20 billion equity raise.
- Microsoft: still positive at $18.6 billion, but planning to access additional funding.
This changes the nature of the arms race. When capex is financed by debt, equity and customer prepayments, the question shifts from “can they afford it?” to “how long will lenders, shareholders and customers keep underwriting it?” Backlogs offer part of the answer: Microsoft reported commercial remaining performance obligations of $677 billion, and Oracle $664 billion — contracted demand that management teams point to as justification.
What to watch next
- 2027 guides. Alphabet has already said capex will rise “significantly.” Amazon, Microsoft and Meta will set their numbers on Q4 calls in early 2027.
- Delivery versus intent. Microsoft’s and Alphabet’s third-party capacity delays are a sign that supply chains — chips, memory, transformers, grid hookups — now set the pace more than budgets do.
- The depreciation curve. Short-lived assets mean rising depreciation for years. Margins will tell whether AI revenue grows faster than the asset base wears out.
- Mix of owned versus leased. More finance leases and neocloud contracts would make reported capex less comparable — and risk harder to see.
The bottom line
The hyperscaler capex arms race in late 2026 is no longer a story of announcements; it is a story of delivery and financing. Roughly three dollars in four of Microsoft’s spend, and about two in three of Alphabet’s infrastructure spend, now go into chips, servers and networking that will be obsolete within about six years. The rest pours into buildings and power infrastructure that will outlive several generations of models. Whether this proves visionary or excessive will depend less on the next guide than on whether foundation models and AI agents generate revenue fast enough to outrun the depreciation clock.
Related reading
- Vertical Integration or Cosplay? Why AI Labs Want Dirt-to-Model Stacks
- The Texas AI Factory Race: Why Hyperscalers Are Betting Tens of Billions on One State
- Microsoft Fairwater and the Rise of the Distributed AI Superfactory
Sources
- Amazon.com, Inc. — Form 10-Q for the quarter ended 30 September 2026 (cash flow statement). https://www.sec.gov/Archives/edgar/data/1018724/000101872426000040/amzn-20260930.htm
- Amazon.com, Inc. — “Amazon.com Announces Third Quarter Results,” 29 October 2026. https://ir.aboutamazon.com/news-release/news-release-details/2026/Amazon-com-Announces-Third-Quarter-Results/
- Alphabet Inc. — Exhibit 99.1, “Alphabet Announces Third Quarter 2026 Results,” 28 October 2026 (SEC 8-K). https://www.sec.gov/Archives/edgar/data/1652044/000165204426000080/googexhibit991q32026.htm
- Alphabet Inc. — 2026 Q3 Earnings Call (CFO remarks). https://abc.xyz/investor/events/event-details/2026/2026-Q3-Earnings-Call-2026-Ujou16CTw9/default.aspx
- Microsoft Corp. — FY27 Q1 earnings release, 28 October 2026 (Investor Relations). https://www.microsoft.com/en-us/investor/earnings/fy-2027-q1/press-release-webcast
- Microsoft Corp. — FY27 Q1 earnings conference call and transcript, 28 October 2026 (CFO Amy Hood remarks). https://www.microsoft.com/en-us/investor/events/fy-2027/earnings-fy-2027-q1 — mirror transcript (third-party): https://stockanalysis.com/stocks/msft/transcripts/718712-q1-2027/
- Meta Platforms, Inc. — “Meta Reports Third Quarter 2026 Results,” 21 October 2026. https://investor.atmeta.com/investor-news/press-release-details/2026/Meta-Reports-Third-Quarter-2026-Results/default.aspx
- Oracle Corp. — “Oracle Announces Q1 Results Driven by Triple Digit Growth in Cloud Infrastructure Revenues,” fiscal Q1 2027 release, 10 September 2026 (incl. 850 MW capacity delivery). https://investor.oracle.com/investor-news/news-details/2026/Oracle-Announces-Q1-Results-Driven-by-Triple-Digit-Growth-in-Cloud-Infrastructure-Revenues/default.aspx
- Oracle Corp. — Q1 FY2027 earnings call transcript (third-party transcript, The Motley Fool), 11 September 2026. https://www.fool.com/earnings/call-transcripts/2026/09/11/oracle-orcl-q1-2027-earnings-call-transcript/
- CNBC — “Oracle (ORCL) Q1 earnings report 2027,” 10 September 2026 (mirror for the 850 MW figure). https://www.cnbc.com/2026/09/10/oracle-orcl-q1-earnings-report-2027.html
- CNBC — “AI buildout hits snag as Google and Microsoft hold capex forecasts,” 29 October 2026 (context on Microsoft’s prior ~$175B calendar-year figure). https://www.cnbc.com/2026/10/29/microsoft-google-ai-capex-estimates.html
Totals in “Adding it up” are AndBeyond.Tech calculations from the sources above.
Images: original illustrations generated for AndBeyond.Tech; no logos or real people depicted.